The Mechanics
The procedural sequence is uncomplicated. The investor identifies positions trading below cost basis; sells those positions to realise the loss; applies the realised loss against realised gains of the same character (short-term losses against short-term gains first, long-term against long-term first, with the residue crossing characters); and then redeploys into a security that preserves the intended market exposure without triggering the wash sale provision. Up to $3,000 of net capital loss may be applied against ordinary income in the year realised, with the remainder carried forward indefinitely. The character of the loss matters because the rate gap between short-term (federal ordinary, currently up to 37%) and long-term (15% or 20%, with possible net investment income tax surcharge) means a short-term loss applied against a short-term gain is generally worth more, in absolute dollars, than the same loss applied against a long-term gain.
A Worked Example
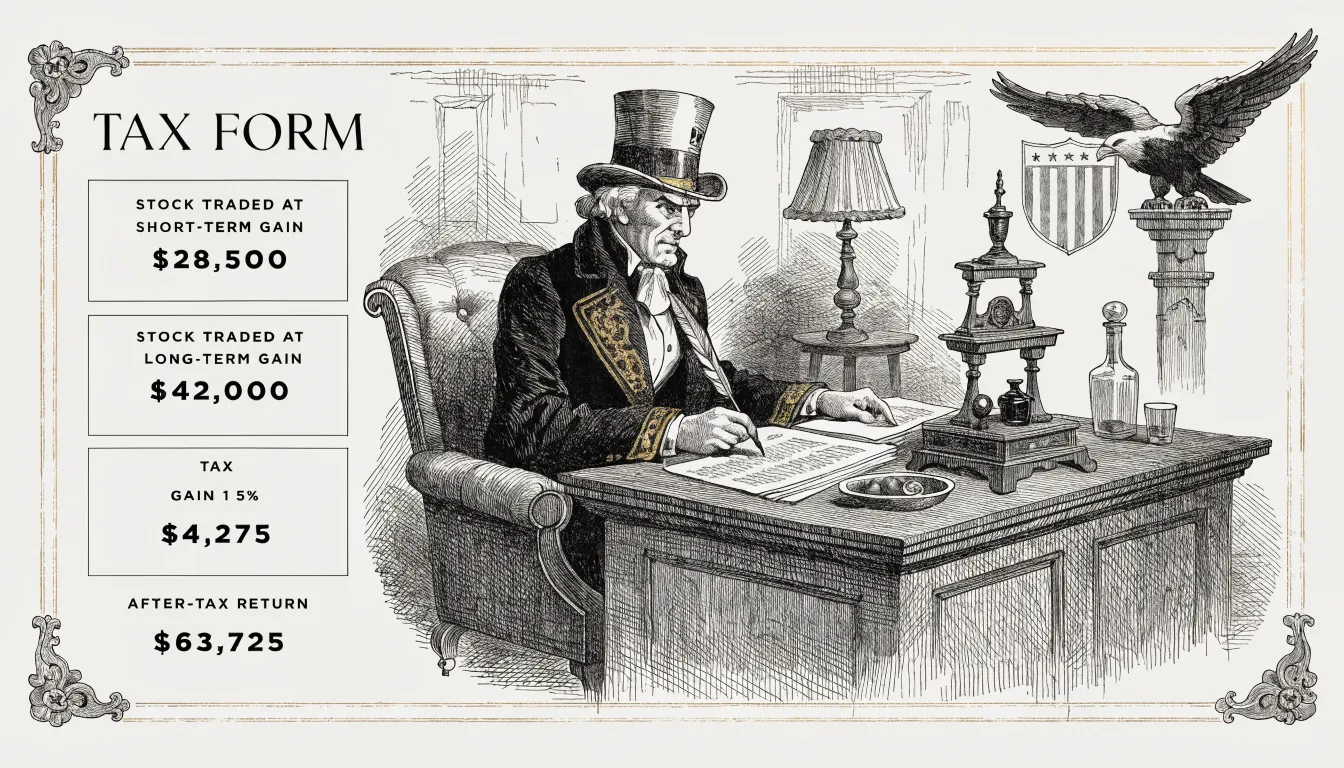
Consider an investor in the 32% federal bracket who has realised $40,000 of short-term gains during the calendar year. The unmitigated liability is $40,000 × 32% = $12,800. Suppose the same account holds Stock A with an unrealised loss of $15,000 and a sector ETF with an unrealised loss of $5,000. Selling both realises $20,000 in losses, reduces the net taxable gain to $20,000, and lowers the year's federal liability to $6,400. The harvested benefit is $6,400 in deferred tax. Reinvested at a 10% compound rate over twenty years, that $6,400 grows to roughly $43,000, subject to verification of the rate assumption against the investor's actual asset mix. The number is not the point; the framework is. The economic value of harvesting is the future value of the deferred amount minus the eventual tax due when the replacement is sold, and absent a sharp adverse move in tax rates that gap is generally positive.
The Wash Sale Rule
The binding constraint on tax-loss harvesting in U.S. accounts is Internal Revenue Code §1091, the wash sale rule. The rule disallows recognition of a loss if the taxpayer acquires “substantially identical” securities within thirty days before or thirty days after the sale, producing a sixty-one-day window centred on the trade date. The disallowed loss is not erased; it is added to the basis of the replacement security, so the deduction reappears at a later sale. The administrative friction, however, is real, and the cross-account application is the trap that catches careful investors most often.
The triggering set, as the IRS interprets it on the available record, includes: selling Stock A at a loss and repurchasing Stock A in the same taxable account; selling Stock A at a loss and writing or buying a call option on Stock A within the window; and — the case that catches the largest number of taxpayers — selling Stock A at a loss in a taxable account while purchasing Stock A in an IRA within the same window. The cross-account version is particularly corrosive because the loss is not merely deferred; the basis adjustment lands in a tax-deferred account where it produces no future deduction. The cash equivalent is permanent loss of the harvested benefit.
The non-triggering set, by contrast, is broad enough to make harvesting workable in practice. Selling Stock A and buying Stock B in the same sector is generally clean; selling an individual semiconductor name and buying a semiconductor ETF is generally clean; selling one S&P 500 vehicle (SPY) and buying a different one (IVV or VOO) tracking the same index is the longest-running grey area, and although the Service has not issued a definitive ruling, the working assumption among most preparers is that distinct vehicles are not substantially identical. The conservative reading is to verify with a qualified preparer rather than rely on practitioner consensus, but the practitioner consensus has held up over a long period.
Timing: Year-End Versus Continuous Harvesting
The two procedural patterns are December harvesting and continuous harvesting, and they carry different operational profiles.
December harvesting concentrates the work in the last two weeks of the tax year, when the full-year picture of realised gains is essentially fixed. The investor totals the year's realised gains, identifies positions with unrealised losses, sells enough to offset the gains plus the additional $3,000 against ordinary income where useful, and either repurchases the original after the thirty-one-day waiting window or substitutes a non-identical proxy immediately. The advantage is informational: the year-end view is the most accurate one available. The cost is that everyone else with similar structures is selling the same widely-held losers at the same time, which can depress execution prices for marginal liquidity. In my own working assumption this December crowding effect is real but second-order relative to the tax benefit captured.
Continuous harvesting takes the opposite approach: the loss is realised when it appears, irrespective of calendar position. A position that drops fifteen percent in March creates an opportunity in March. The advantage is that more total loss is captured, since some of the March losers will have recovered by December and the harvest window will have closed. The disadvantage is the elevated risk of inadvertent wash sales, particularly where the same names recur in the trading book. Continuous harvesting requires a wash sale tracking log; the alternative is to discover at year-end that several months of harvested losses have been disallowed by repurchases the investor did not flag.
Active Trading and Section 475(f)
For day traders and swing traders the standard wash sale framework is awkward, because the same securities are bought and sold repeatedly within compressed windows and the rule disallows nearly every loss the trader attempts to realise. The formal solution is the Section 475(f) mark-to-market election, which exempts qualifying full-time traders from the wash sale rule entirely. All positions held by an electing trader are marked to market at year-end, all gains and losses are treated as ordinary income, and the wash sale provisions do not apply.
The election is not a casual decision. It is irrevocable absent further IRS consent, it converts long-term capital gains (taxed at 15% or 20%) into ordinary income (taxed at up to 37%), and it requires meeting the trader-tax-status threshold the Service applies on a facts-and-circumstances basis. The right sequence is professional review of the account's profile first, then election, not the reverse; an investor who elects and subsequently fails the trader-status test has converted a favourable rate to an unfavourable one with no offsetting benefit. The clinical observation from my own practice is that the cohort for whom the election produces clear after-tax improvement is narrower than the marketing literature suggests — primarily traders whose realised positions are short-term-dominant, who carry consistent activity throughout the year, and whose loss profile is sufficiently bunched that wash sale disallowance under the default rules would erase a meaningful share of the deduction.
What Harvesting Is Worth
The recoverable benefit scales with portfolio size, marginal tax rate, and the realised-gain trajectory of the account.
| Portfolio Size | Annual Gains | Harvested Losses | Tax Savings (32% bracket) |
|---|---|---|---|
| $50,000 | $8,000 | $5,000 | $1,600 |
| $200,000 | $30,000 | $15,000 | $4,800 |
| $500,000 | $75,000 | $40,000 | $12,800 |
| $1,000,000 | $150,000 | $80,000 | $25,600 |
The published academic estimates — broadly the work cited in the practitioner literature on after-tax indexing — place the long-run incremental contribution of disciplined harvesting at approximately 0.5% to 1.5% per year of after-tax return, with the upper end concentrated in higher-volatility regimes where more positions trade through their cost basis. The estimate has the methodological character of a backtest, with the usual replication caveats: the realised contribution in a particular account depends on basis dispersion, on the marginal rate at deferral versus the marginal rate at eventual recognition, and on the discipline with which the wash sale rule is administered. The boutique academic literature on the topic (Arnott, Berkin, Ye, and others) develops this with greater precision than an encyclopedia entry can responsibly summarise; readers seeking the formal treatment should consult those sources directly rather than rely on the rough table above.
The Common Errors
Several patterns recur in the harvesting work I see across HNW accounts, and they are worth naming directly. The first is harvesting without a replacement, which converts a tax-management exercise into an unintentional allocation decision. If the original position represented a sector view the investor wishes to maintain, the harvest must be paired with a non-identical proxy of broadly similar exposure; otherwise the investor has accidentally reduced the relevant beta and may miss a recovery the original thesis anticipated.
The second is treating harvested losses as a free benefit rather than a basis adjustment. The deduction realised today reduces the basis of the replacement, which means a larger gain (and larger eventual tax) when the replacement is sold. The mathematics still favour deferral in nearly every realistic scenario, but the deferred liability is real and the analyst should treat the harvested amount as a timing benefit rather than a cancellation of obligation.
The third is the cross-account wash sale, discussed above, which a surprising share of investors trigger inadvertently through automatic dividend reinvestment in retirement accounts. An automatic reinvestment of a dividend into the same security inside an IRA, falling within the sixty-one-day window of a taxable-account harvest, is sufficient to disallow the loss. The remediation is to suspend automatic reinvestment in the relevant account during the window; the alternative is to discover the disallowance at preparation time, when there is no remaining flexibility to undo it.
The fourth is the reverse error: refusing to sell a winning position because of the embedded gain, on the theory that any sale crystallises a tax that further deferral would avoid. The position becomes, in chess terms, a piece the investor cannot move because the immediate cost obscures the structural improvement that motion would produce. If the position no longer fits the thesis, it should be sold for thesis reasons; harvested losses, properly accumulated, are precisely the instrument that softens the realised gain. The tax tail should not direct the investment decision in either direction.
A Practical Note
The framework above describes what disciplined harvesting can do under typical conditions. It does not describe what it cannot do. It does not improve the underlying investment decision; an account harvesting losses on positions that should not have been owned is recovering a fraction of an avoidable error rather than producing alpha. It does not protect against the eventual reckoning at sale of the replacement. It does not eliminate the risk that future tax rates rise in the interval between deferral and recognition, in which case the deferred liability is worse, not better. The benefit is conditional on the rate environment, on the investor's discipline with the wash sale provisions, and on the basis dispersion the portfolio happens to carry through any given year. In well-managed accounts those conditions hold often enough that the accumulated benefit, over a decade or two, is meaningful; readers wishing to translate the framework into specific filing decisions should do so with a qualified preparer rather than from this article.
See also: Capital Gains Tax: What Traders Need to Know · IRA · Budgeting · Position Sizing and Risk Management · ETFs